Natural gas
Natural gas prices
A warm start to November is putting downward pressure on U.S. natural gas prices. Our forecast assumes 13% fewer heating degree days (HDDs) across the United States in November compared with the 10-year average for the month. We now expect 3,840 billion cubic feet of natural gas will be held in storage at the end of November, 67 Bcf more than we forecast last month. The Henry Hub spot price in our forecast averages $2.87 per million British thermal units (MMBtu) from November through March, 16% less than last month’s forecast and 36% less than last winter.
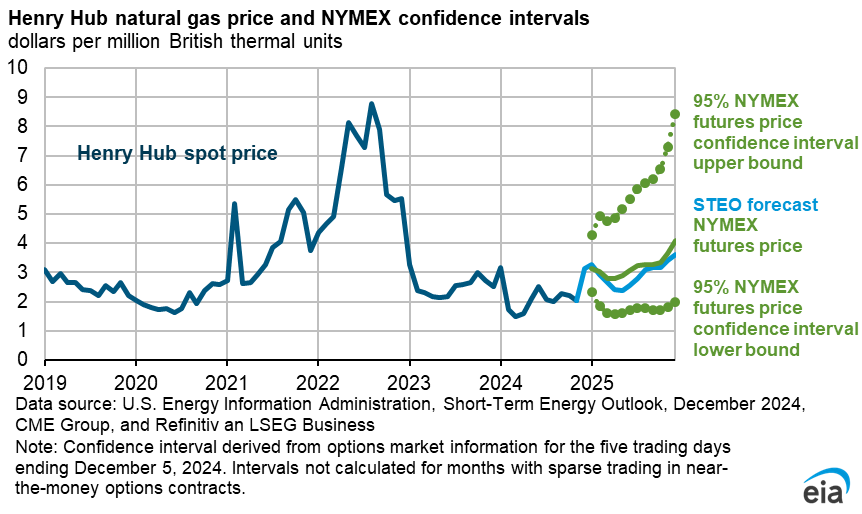
We expect continuing growth in U.S. natural gas production to put downward pressure on Henry Hub prices in the coming year. Production growth outpaces increasing demand from domestic sources and exports, leaving U.S. natural gas inventories about 3% above 2026 levels on average. We forecast Henry Hub will average $2.88/MMBtu in 2027, down from $3.37/MMBtu this year.
At the same time, international natural gas prices have risen to the highest levels since December 2022, supporting U.S. liquefied natural gas (LNG) export economics. Since the U.S.-Iran conflict began on February 28, the monthly near-month futures price at the European benchmark Dutch Title Transfer Facility rose from an average of $11.27/MMBtu in February 2026 to an average of $28.51/MMBtu in October, according to data from Bloomberg, L.P. Similarly, the Japan-Korea Marker near-month futures price in East Asia rose from an average of $10.82/MMBtu in February to $28.59/MMBtu in October. Tanker strikes and other logistical disruptions have continued to limit LNG exports through the Strait of Hormuz, which remain well below pre-war levels.

LNG exports
We forecast LNG exports to average 17.6 billion cubic feet per day (Bcf/d) in 2026 and 19.0 Bcf/d in 2027, up from 15.1 Bcf/d in 2025, as new export capacity ramps up. The seventh and final train of the Corpus Christi Stage 3 export facility (1.5 Bcf/d nominal capacity) reached substantial completion in late August. Golden Pass LNG has reported a sustained increase in feedgas demand in recent weeks following months of slower-than-expected exports from Train 1 since its April 2026 startup. U.S. LNG exports also received a boost in October as Cove Point LNG (0.8 Bcf/d nominal capacity) concluded planned maintenance on October 12.

Residential and commercial demand
We expect U.S. natural gas consumption in the residential and commercial sectors to average 36.4 Bcf/d during the 2026–2027 winter heating season (November–March), down 3.8% from last winter. Warmer weather—compared with last winter—reduces space heating demand.

Our forecast includes 1% fewer HDDs this winter compared with last winter. In addition to the warm November to start the winter, January HDDs are forecast to decline 10% from last year, accompanied by a 10% decrease in residential and commercial natural gas consumption. Forecast year-over-year declines in natural gas consumption in the residential and commercial sectors from November through February are partly offset by rising consumption in March. HDDs in March are forecast to increase 31% from last winter, with residential and commercial consumption rising by 17%.
The National Oceanic and Atmospheric Administration’s U.S. Winter Outlook reflects the influence of a strengthening El Niño and favors above-average temperatures across the northern United States from December through February. However, the timing and severity of cold weather remains uncertain. Severe cold weather events, particularly in January and February, could also increase winter demand above our forecast and cause temporary spikes in prices.