
Electricity Monthly Update
Resource Use: July 2026
Supply and fuel consumption
In this section, we look at the resources used to produce electricity. Generating units are chosen to run primarily on their operating costs, of which fuel costs account for the lion's share. Therefore, we present below, electricity generation output by fuel type and generator type. Since the generator/fuel mix of utilities varies significantly by region, we also present generation output by region.
Generation output by region
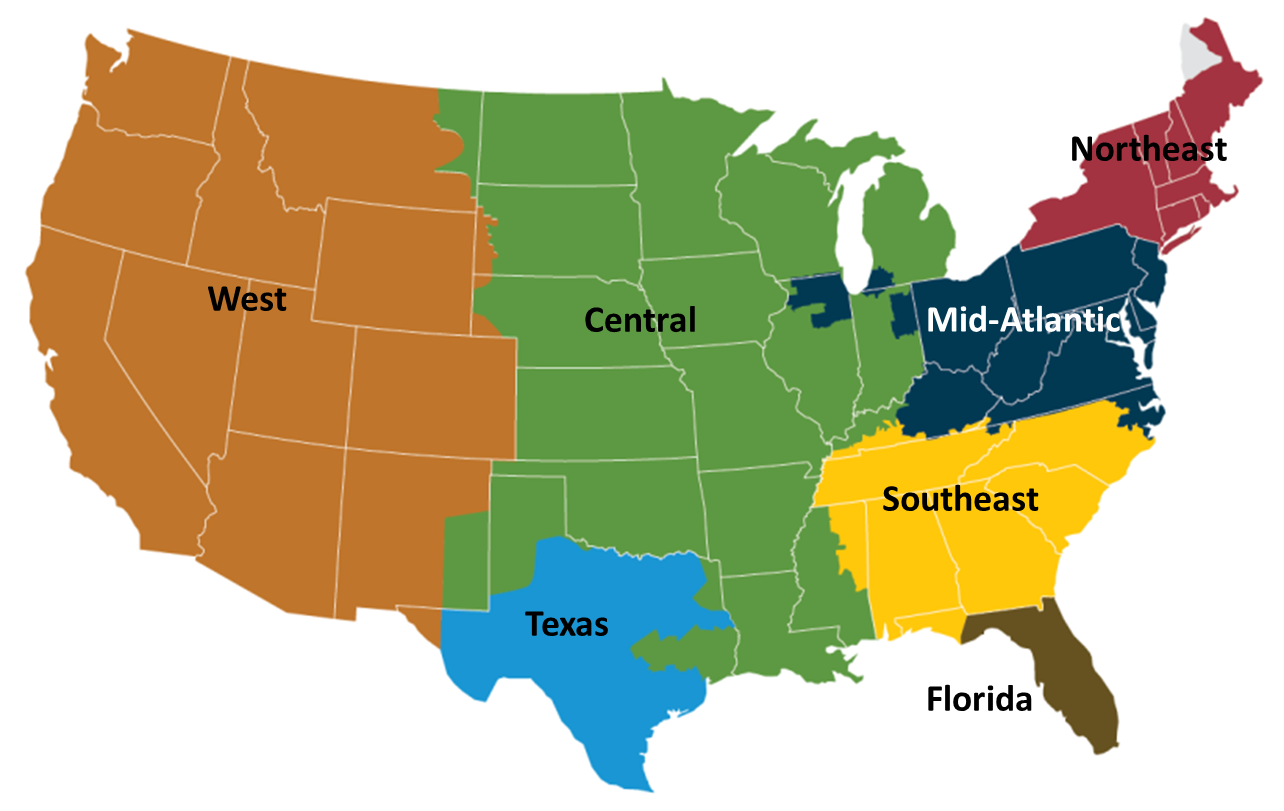
Net electricity generation in the United States increased 1.7% compared to July 2025. The changes in electricity generation from the previous July were mixed throughout the country. The West, Texas, and Florida all saw a year-over-year increase in electricity generation, while the Northeast, MidAtlantic, Southeast, and Central regions all saw a decrease in electricity generation when compared to the previous year. The region-by-region differences in the change in electricity generation were generally a result of warmer weather in the western parts of the country compared to last July, and cooler weather across much of the eastern United States.
Electricity generation from coal saw year-over-year increases in Texas and Florida, while the West, Southeast, Central, MidAtlantic, and Northeast saw year-over-year decreases in coal generation. All regions saw an increase in natural gas generation compared to July 2025, with the exception of MidAtlantic and Northeast, where natural gas generation decreased compared to the previous July. Other renewable generation increased in all parts of the country, except for the West.
Fossil fuel consumption by region
The chart above compares coal consumption in July 2026 and July 2025 by region and the second tab compares natural gas consumption by region over the same period. Changes in coal and natural gas consumption were similar to their respective changes in coal and natural gas generation.
The third tab presents the change in the relative share of fossil fuel consumption by fuel type on a percentage basis, calculated using equivalent energy content (Btu). This highlights changes in the relative market shares of coal, natural gas, and petroleum. The West, Southeast, Central, and MidAtlantic saw their shares of natural gas increase at the expense of coal, whereas Texas and Florida saw their shares of coal increase at the expense of natural gas.
The fourth tab presents the change in coal and natural gas consumption on an energy content basis by region. The changes in total coal and natural gas consumption were similar to the changes seen in total coal and natural gas net generation in each region.
Fossil fuel prices
To gain some insight into the changing pattern of consumption of fossil fuels over the past year, we look at relative monthly average spot fuel prices. A common way to compare fuel prices is on an equivalent $/MMBtu basis as shown in the chart above. The average price of natural gas at Henry Hub decreased from the previous month, going from $3.15/MMBtu in June 2026 to $2.93/MMBtu in July 2026. The natural gas price for New York City (Transco Zone 6 NY) also decreased slightly from the previous month, going from $2.42/MMBtu in June 2026 to $2.30/MMBtu in July 2026. The average spot price of Central Appalachian coal was unchanged from the previous month at $3.28/MMBtu in July 2026.
A fuel price comparison based on equivalent energy content ($/MMBtu) does not reflect differences in energy conversion efficiency (heat rate) among different types of generators. Gas-fired combined-cycle units tend to be more efficient than coal-fired steam units. The second tab shows coal and natural gas prices on an equivalent energy content and efficiency basis. The Henry Hub natural gas price ($23.47/MWh) saw a decrease from the previous month ($25.26/MWh) and was below the Central Appalachian coal price ($35.42/MWh) in July 2026. The price of natural gas at New York City ($18.39/MWh) also saw a decrease compared to the previous month ($19.37/MWh) and was also below the Central Appalachian coal price ($35.42/MWh).
The conversion shown in this chart is done for illustrative purposes only. The competition between coal and natural gas to produce electricity is more complex. It involves delivered prices and emission costs, the terms of fuel supply contracts, and the workings of fuel markets.